The Ultimate Guide to Finding the Best Homeowners Insurance
Best homeowners insurance sets the stage for this enthralling narrative, offering readers a glimpse into a story that is rich in detail and brimming with originality. In a world where protecting your most valuable asset is paramount, understanding the ins and outs of homeowners insurance is crucial.
This guide will take you on a journey through the importance of homeowners insurance, factors to consider when choosing the best policy, different types of policies available, and tips for saving money while ensuring optimal coverage.

Homeowners insurance is crucial for protecting one’s property from unforeseen events and disasters. It provides financial security and peace of mind in the face of potential risks.
Not having homeowners insurance can lead to significant financial consequences. In the event of a disaster or unexpected damage to your home, you would be responsible for covering all repair costs out of pocket. This can result in a substantial financial burden that may be difficult to recover from without insurance coverage.

When selecting the best homeowners insurance policy, there are several critical factors to take into account to ensure you have the right coverage for your needs. These factors include coverage options, deductibles, premiums, and customer service. It is also important to compare the coverage limits offered by different insurance providers and consider how factors like location, home value, and personal belongings can impact your insurance choices.
When choosing homeowners insurance, it is essential to consider the different coverage options available. This includes coverage for your dwelling, personal property, liability protection, and additional living expenses in case your home is uninhabitable. Make sure the policy you select provides adequate coverage for your specific needs.
Deductibles are the amount you have to pay out of pocket before your insurance coverage kicks in. It is crucial to choose a deductible that you can comfortably afford in the event of a claim. Remember that higher deductibles typically result in lower premiums, but you need to strike the right balance based on your financial situation.
Premiums are the amount you pay for your insurance coverage. While it is tempting to choose the cheapest premium available, it is important to ensure that you are not sacrificing essential coverage for a lower price. Compare premiums from different providers to find a balance between affordability and adequate coverage.
Customer service is another crucial factor to consider when selecting homeowners insurance. Look for insurance providers with a reputation for excellent customer service, as you want to ensure that the company will be responsive and helpful in case you need to file a claim or have any questions about your policy.
The location of your home, its value, and the contents inside can all influence your homeowners insurance choices. Homes in areas prone to natural disasters may require additional coverage, while high-value homes may need higher coverage limits. It is also essential to consider the value of your personal belongings and whether you need additional coverage for expensive items like jewelry or electronics.

When it comes to homeowners insurance, there are several types of policies available to choose from. Understanding the differences between HO-1, HO-2, HO-3, and HO-5 policies can help you select the one that best suits your needs.
The HO-1 policy is a basic form of coverage that provides protection against specific perils listed in the policy. This type of policy is rarely used today due to its limited coverage and availability.
HO-2 policies offer more comprehensive coverage than HO-1 policies. They protect against a specific list of perils, typically including common incidents like fire, theft, vandalism, and more. This type of policy is suitable for homeowners looking for more coverage options than what an HO-1 policy provides.
The HO-3 policy is the most common type of homeowners insurance policy. It provides coverage for the structure of your home against all perils except those specifically excluded in the policy. This type of policy is suitable for most homeowners and offers a good balance between coverage and affordability.
HO-5 policies offer the most comprehensive coverage among all homeowners insurance policies. They provide coverage for both the structure of your home and personal belongings against all perils, except those excluded in the policy. This type of policy is suitable for homeowners who want extensive coverage and are willing to pay higher premiums for it.
In addition to the standard homeowners insurance policies, there are additional coverage options available to enhance your protection. These options include:
Flood Insurance
Protects your home and belongings from flood damage, which is not covered under standard homeowners insurance policies.
Personal Liability Protection
Covers you in case someone is injured on your property or if you accidentally damage someone else’s property. This coverage can help protect you from financial loss due to lawsuits.By understanding the differences between these homeowners insurance policies and additional coverage options, you can make an informed decision when choosing the best policy to protect your home and assets.

When it comes to homeowners insurance, finding ways to save money while still maintaining adequate coverage is essential. Here are some tips to help you reduce your insurance premiums without compromising on protection.
Raising your deductible can lead to lower insurance premiums. However, make sure you have enough savings set aside to cover the higher deductible in case of a claim.
Many insurance companies offer discounts if you bundle your homeowners insurance with other policies such as auto insurance. This can result in significant savings on your overall insurance costs.
Installing a home security system or making improvements to your home’s security features can make you eligible for discounts on your homeowners insurance. This is because a safer home is less likely to experience theft or damage.
Insurance companies often use credit scores to determine premiums. By maintaining a good credit score, you may qualify for lower insurance rates. Be sure to regularly check your credit report for any errors that could negatively impact your score.
As your circumstances change, so do your insurance needs. Review your coverage annually to ensure you are not paying for more coverage than you need. Adjusting your coverage can help you save money on your homeowners insurance.
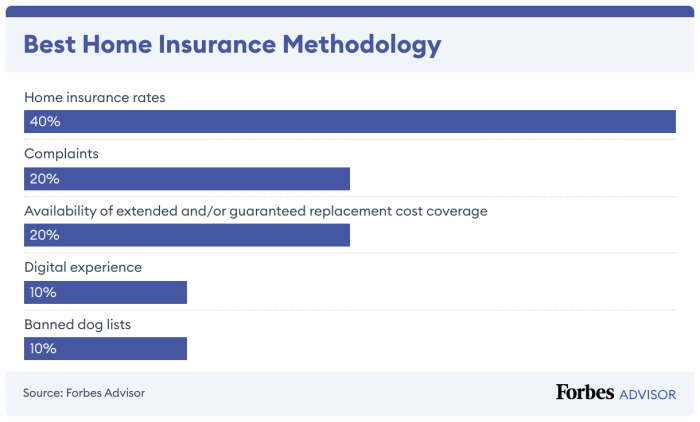
In conclusion, finding the best homeowners insurance is not just about getting the most affordable policy, but also about securing comprehensive coverage tailored to your specific needs. By considering the factors discussed in this guide and exploring various policy options, you can make an informed decision that protects your home and assets effectively.
Now, armed with valuable knowledge, you can navigate the complex world of homeowners insurance with confidence and peace of mind.
What factors should I consider when choosing the best homeowners insurance?
Key factors to consider include coverage options, deductibles, premiums, and customer service quality.
What are the differences between HO-1, HO-2, HO-3, and HO-5 policies?
HO-1 is basic coverage, HO-2 is broad coverage, HO-3 is special coverage, and HO-5 is comprehensive coverage.
How can I save money on homeowners insurance?
You can save money by reducing premiums without compromising coverage, qualifying for discounts, and investing in home improvements or security systems.